Product update 4 min read
Deal Management: From First Contact to Funded, All in One Workspace
A full lightweight DMS/F&I workflow: credit files, encrypted SSNs, itemized tax and fees, lender tracking and a lender-ready credit application PDF.
Deal Management just grew from a simple deal recap into a real lightweight DMS/F&I workflow — the kind of thing a lender’s underwriter can actually approve a loan against, not just a dealer’s own notes about one. Here’s everything that’s new.
A real credit file, not just a name and a phone number
A deal used to hold a customer record built for a sales follow-up. Now it holds what a lender actually needs to say yes:
- Full legal name, suffix, date of birth, driver’s license with state and expiration, and both phone numbers.
- A co-buyer carrying the identical set of fields, since a lender who can’t pull a co-signer’s credit can’t approve the loan either.
- Current and previous residence, with time-at-address and monthly payment.
- Itemized employment & income — base pay, commission, tips, overtime, and bonus each get their own field, and an hourly rate plus weekly hours will estimate the monthly base for you (still just a normal, editable number).
A Social Security number gets treated like one
Nothing else in the system holds anything this sensitive, so nothing else in the system needed this much care:
- Encrypted at rest — the database column holds ciphertext, never plaintext.
- Masked everywhere — every screen shows
*--1234; the real value never renders into a page on load. - Reveal is a witnessed act — only a manager can reveal a full number, and every reveal writes a permanent, timestamped entry to that deal’s activity log.
- Documents stay private — pay stubs and bank statements live outside the public web, served only through an authenticated link, not a public URL like a vehicle photo.
Tax and fees you can actually explain
Sales tax stopped being a number someone typed in, and started being a real calculation:
- Tax now resolves an actual jurisdiction — the deal’s registration state, falling back to the customer’s, then the dealership’s — and applies every active rule for that state at once, so a state tax and a local tax can both land correctly. Rates cap where the law caps them.
- A manager can still override the result by hand, but never silently — an override requires a typed reason and is logged against the deal, permanently.
- Every fee — doc fee, title, registration, temp tag, e-filing, dealer add-ons, and more — is its own line, each with its own taxable and financed flags. A fee marked not-financed drops out of the loan amount and shows up in Due at Signing instead.
- Warranty, Vehicle Service Contract, and GAP are now a real dealer-priced product catalog, picked per deal — not one flat “warranty” number pretending every car gets the same coverage.
Track a deal from first contact to funded
A deal has a real lifecycle now — sixteen stages, from New and Credit App Started through Approved, Ready for Lender Submission, Contracted, and Funding Pending, to Funded and Delivered — wide enough to cover a cash deal closed in an afternoon or a submission that’s still waiting on a stip three lenders deep.
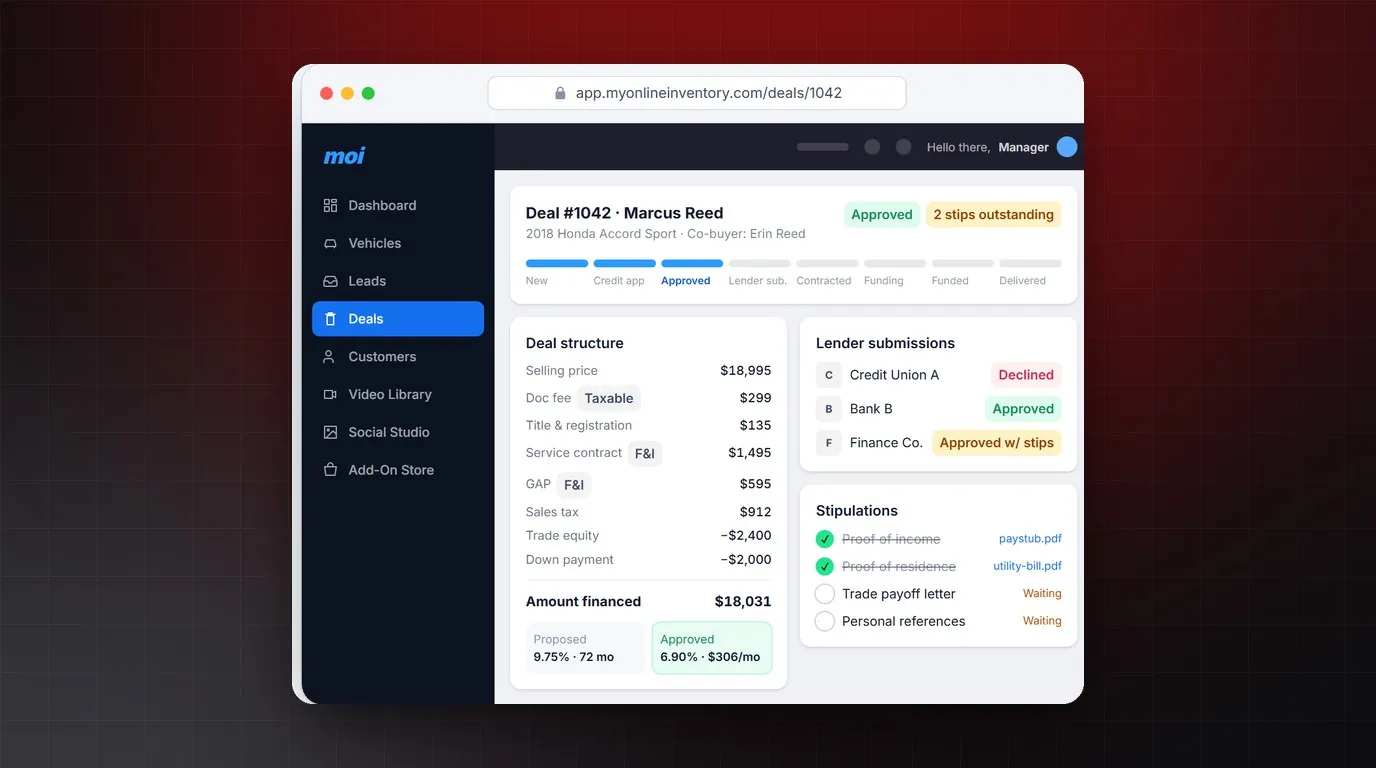
- Proposed vs. Approved Financing are now two different sets of numbers, never one field doing both jobs — so an estimated 9.75% APR can never be mistaken for an actual 6.9% approval.
- Dealers keep their own lender list — name, contact, submission email, dealer number — right in Deal Management.
- A deal can be shopped to more than one lender at once, each tracked independently: Credit Union A — Declined. Bank B — Approved. Finance Co. — Approved with stips. The dealer picks a winner; nothing decides for them.
- Trade-ins now track allowance, payoff, and equity (positive or negative, both handled correctly), plus an estimated value and payoff reference number.
Stipulations, documents, and a signature that means something
- A stipulations checklist tracks exactly what a conditional approval is waiting on — proof of income, proof of residence, a trade payoff letter — each one optionally linked to an uploaded document. An outstanding count sits right in the deal header.
- Credit authorization is a real consent record: the customer signs by hand on the screen, and the system captures the timestamp, IP address, and device — never something the browser could hand-feed. Once signed, it’s permanent; there’s no edit button, on purpose.
Two purpose-built documents
- Deal Summary PDF — a clean, customer-facing recap. No cost, no gross, no SSN.
- Credit Application & Deal Submission PDF — the real underwriter package: applicant, co-applicant, residence, employment, vehicle, trade, requested financing, and the signed authorization. This is the one document in the whole system that shows a full SSN — gated to managers, and download-only by design, so it’s never accidentally auto-emailed.
Small things that add up
Set your tax rate, fee defaults, and lender list once in Dealer Settings — every new deal inherits them, with room to override. Address fields across Leads, Deals, and Dealer Info now suggest real addresses as you type. And every deal on your dashboard has a quick-actions menu for downloading its PDF without opening it first.